About me

Hi, I’m Ayoub.

I’m a quant and a PhD student in mathematics. I work with financial models, numerical methods, and the assumptions behind them.

This is where I share independent projects and write about the ideas I’m working through.

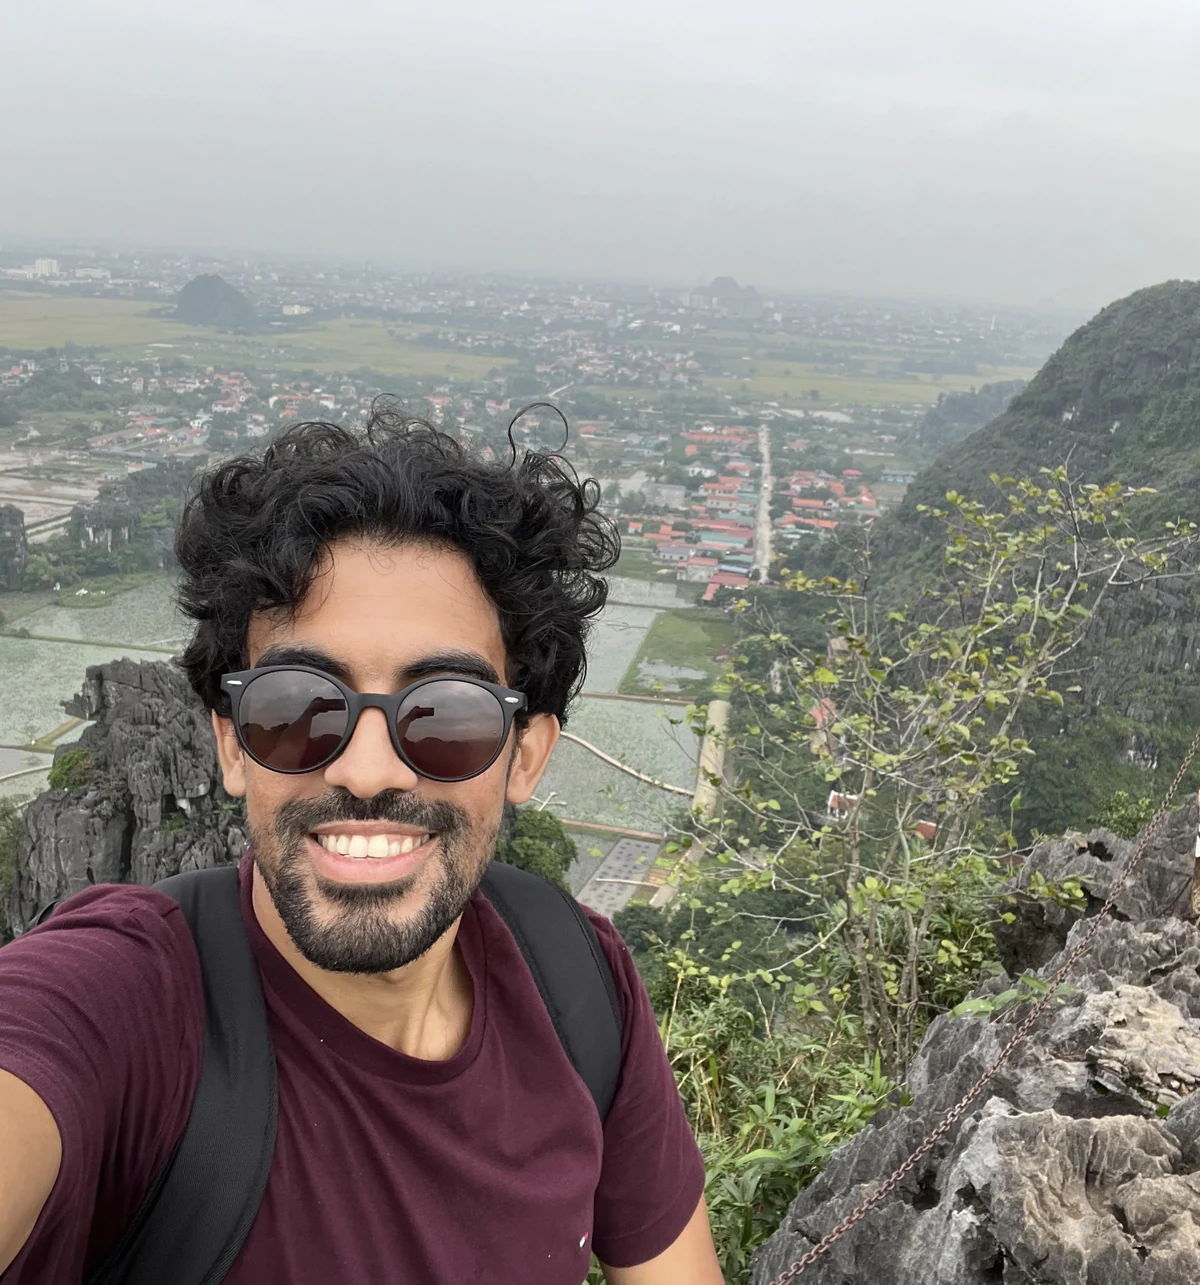
Ayoub Makroz smiling at a hillside viewpoint.
Fig 0 Portrait
Scroll to explore
Fig 1 Option payoff
Call · strike 100

Quantitative finance

Understanding the model.
Questioning the assumptions.

I work in quantitative finance, with experience in financial modelling and model validation, including FX pricing and risk models.

I’m interested in how a model turns a financial question into a mathematical one—and what gets lost along the way. Pricing, sensitivities, numerical behaviour, and the interpretation of risk are all part of that question.

The figure shows a simple option’s payoff at expiry, before premium. Switch between a call and a put.

Fig 2 Stop or continueDynkin game
Both continue · t = 0

Game theory and Dynkin games

Stopping decisions
in Dynkin games.

I am a PhD student in mathematics at Wrocław University of Science and Technology. My research is about game theory and Dynkin games.

A Dynkin game has two players. Each player selects a time to stop a random process. The payoff depends on which player stops first. The payoff also depends on the time and the state of the process.

I examine how each player selects a stopping time when the other player can also stop the game.

Select Play a round to start the example. Orange cells show where Player 1 stops. Blue cells show where Player 2 stops. Gray cells show where both players continue.

About the example

This figure shows an example game. It does not show a result from my research. Player 1 maximizes the expected payoff. Player 2 minimizes the expected payoff.

The game has 12 steps. The state follows a bounded random walk between −5 and 5. Each step selects an upward or downward change with equal probability. At a boundary, an outward change does not change the state.

If Player 1 stops, the payoff is x − 1. If Player 2 stops, the payoff is x + 1. At step 12, the payoff is x. The displayed payoff includes a discount factor of 0.85 for each step.

Backward induction determines the stopping regions. Before step 12, Player 1 has priority if both players stop at the same time.

Fig 3 Monte Carlo sampling
500 samples

Projects

From an idea
to an implementation.

My independent projects will live here: implementations, numerical experiments, and explanations of the choices behind them.

I’m interested in the full process—from the mathematical formulation to the code, the checks, and the limitations.

First projects coming soon.

An interactive example: estimate π by sampling points in a square and counting those inside the circle.

Fig 4 Numerical differentiation
h = 1

Writing

Make the argument.
Show the working.

Notes, worked examples, and longer articles on quantitative finance, numerical methods, and mathematics.

I want the assumptions to be visible and the calculations to be something a reader can follow, check, and build on.

First articles coming soon.

The orange tangent uses a central finite difference. Reduce its step to bring it closer to the exact derivative.